Coverage Options
The parts I build a home policy from, laid out one at a time so I can match every limit to your property.
Cover, Piece By Piece
A home policy is not one thing. I build it from separate limits, and each one answers a different kind of bad day.
Structure And Dwelling
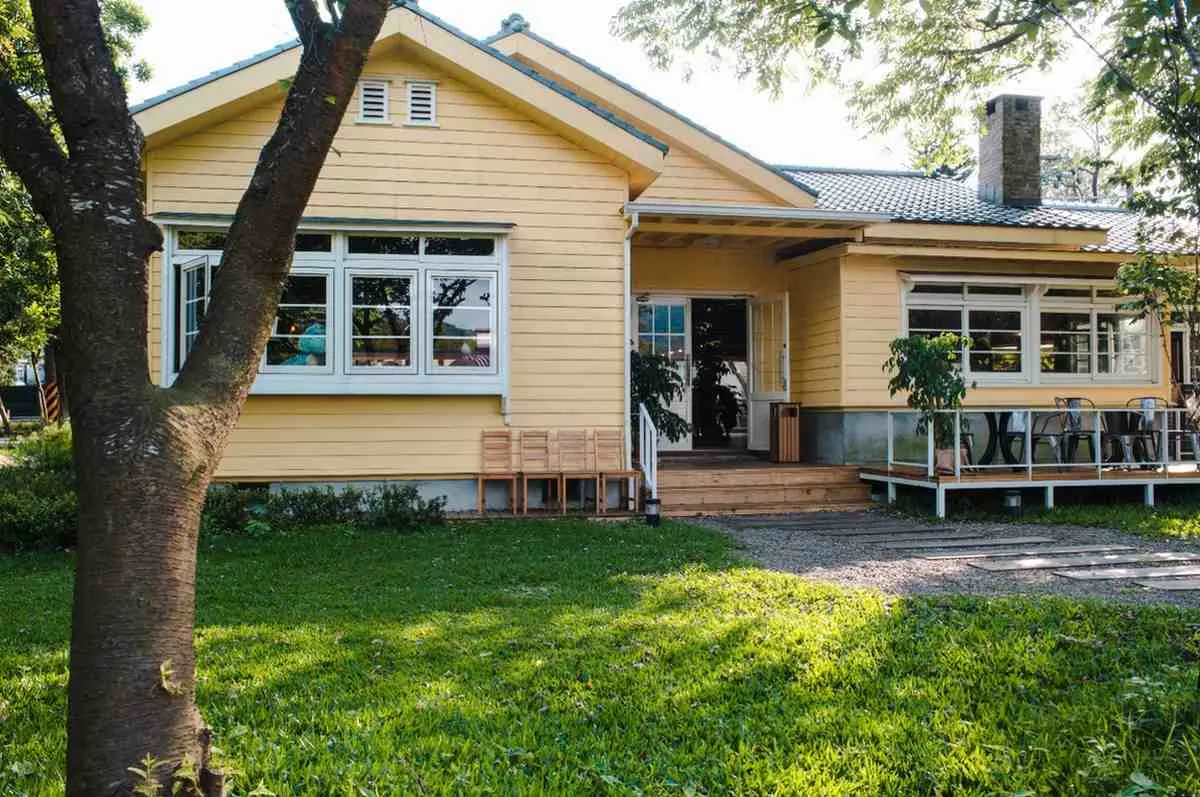
The walls, roof, floors and everything fixed into the building. I set this limit against rebuild cost rather than market value, because materials and labor are what a repair actually eats through.
- Fire, smoke and lightning damage to the building
- Wind and hail damage to roof coverings and siding
- Sudden water escape from plumbing inside the walls
- Impact damage from falling trees or branches
Belongings Inside
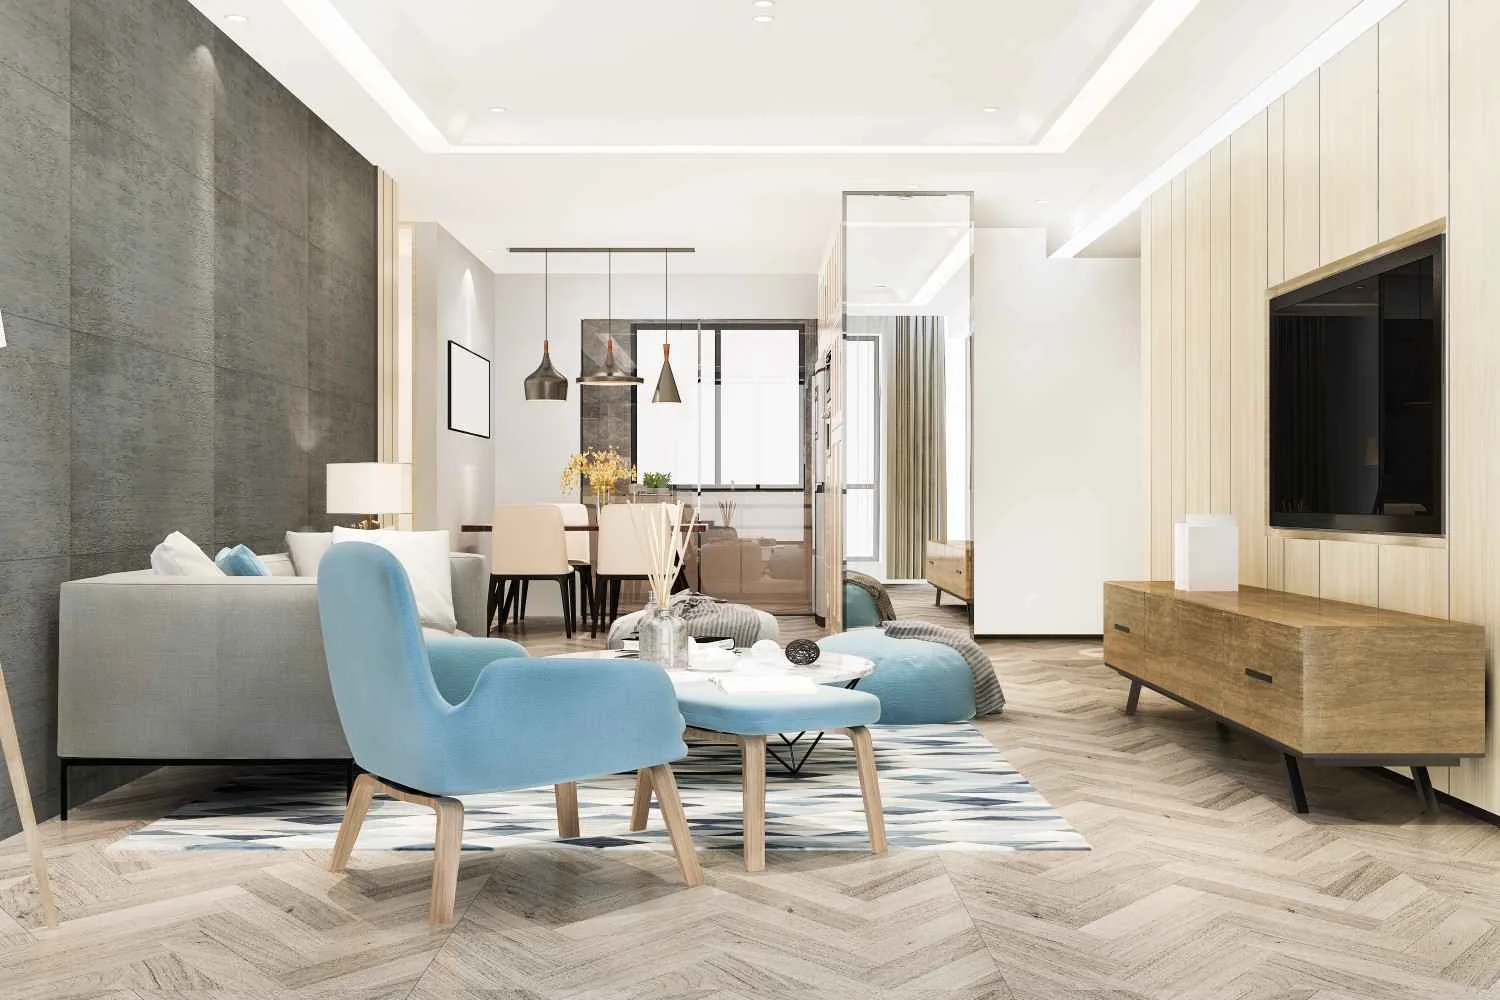
Furniture, clothing, electronics, kitchenware and the hundred small things that make a house livable. Contents get a limit of their own, and I list higher value pieces on their own so they are covered for what they are really worth.
- Replacement value rather than second hand value
- Cover that follows belongings away from the property
- Separate listings for jewelry, instruments and collections
- Theft and vandalism inside the home
Storm And Water
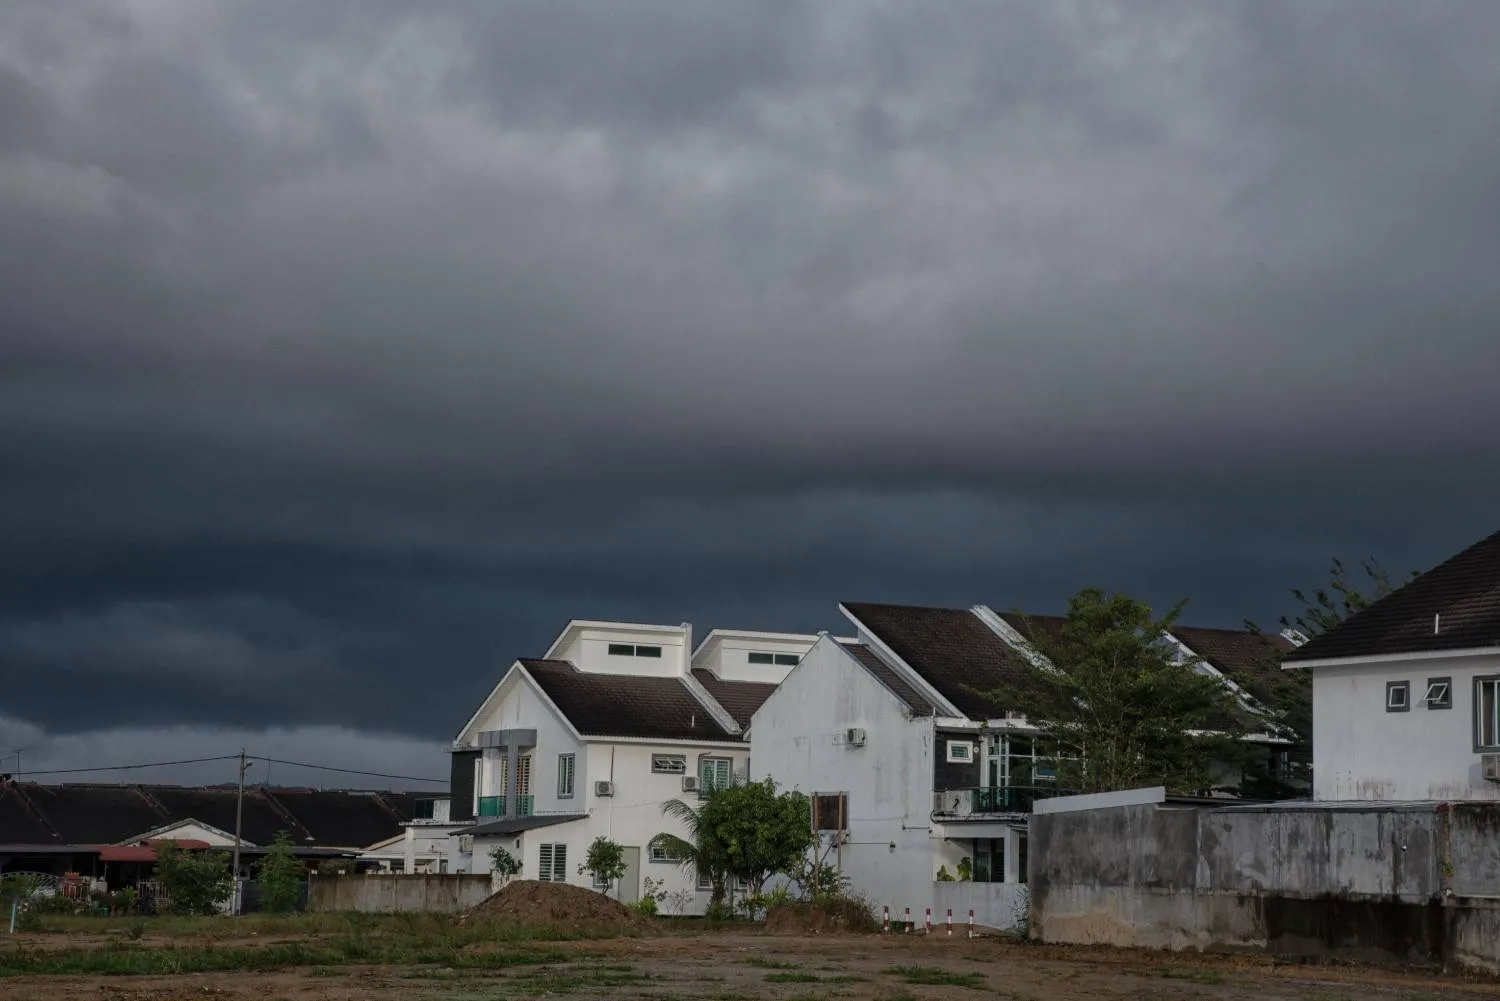
Weather does the most predictable damage and still catches the most people out. Wind, hail and sudden indoor leaks sit inside the policy, and where water rises from outside I arrange separate cover to run alongside it.
- Wind driven rain entering through storm damage
- Hail damage to roofing, gutters and outbuildings
- Burst pipes, failed tanks and overflow indoors
- A straight answer from me on whether you need rising water cover
Liability And Living Costs
The parts of a policy nobody thinks about until they matter. Liability answers for injury or damage your household is responsible for, and I make sure additional living cost keeps a roof overhead while the real one goes back together.
- Injury to a guest on the property
- Accidental damage caused to a neighbor
- Legal defense costs tied to a covered claim
- Somewhere to stay while repairs are running
Worth Adding To A Policy
Optional pieces I add when a standard schedule leaves a gap wide open.
-
Outbuildings And Fencing
Detached garages, sheds, workshops and boundary fencing carry a limit of their own, and it is the one I see underestimated most often.
-
Home Office Equipment
Work machines, monitors and desk setups quietly run past the everyday electronics limit, so I check yours before it ever matters.
-
Service Line Cover
The buried pipes and cables running from the street to your building are yours to fix, and fixing them means tearing up the yard.
-
Sewer And Drain Backup
A backed up drain can ruin a finished basement in one evening, and the standard water wording will not go near it.
-
Identity Restoration
Help and cost cover for putting your records straight again once somebody has misused your personal details.
-
Green Rebuild Allowance
Extra allowance so I can finish a repair to current building standards instead of the ones in force when the house went up.
Getting Covered Is Quick
No long forms. Walk three short steps with me and you will know exactly where your home stands.
01
Share The Basics
Send me the address, how old the roof is, and a rough idea of what you keep inside. Ten minutes at most.
02
Weigh The Options
I lay the quotes out beside each other so a lower monthly figure never hides a thinner limit.
03
Lock It In
Pick what suits the way you live, sign it off online, and I will send the paperwork over the same day.